Finance
5 mins
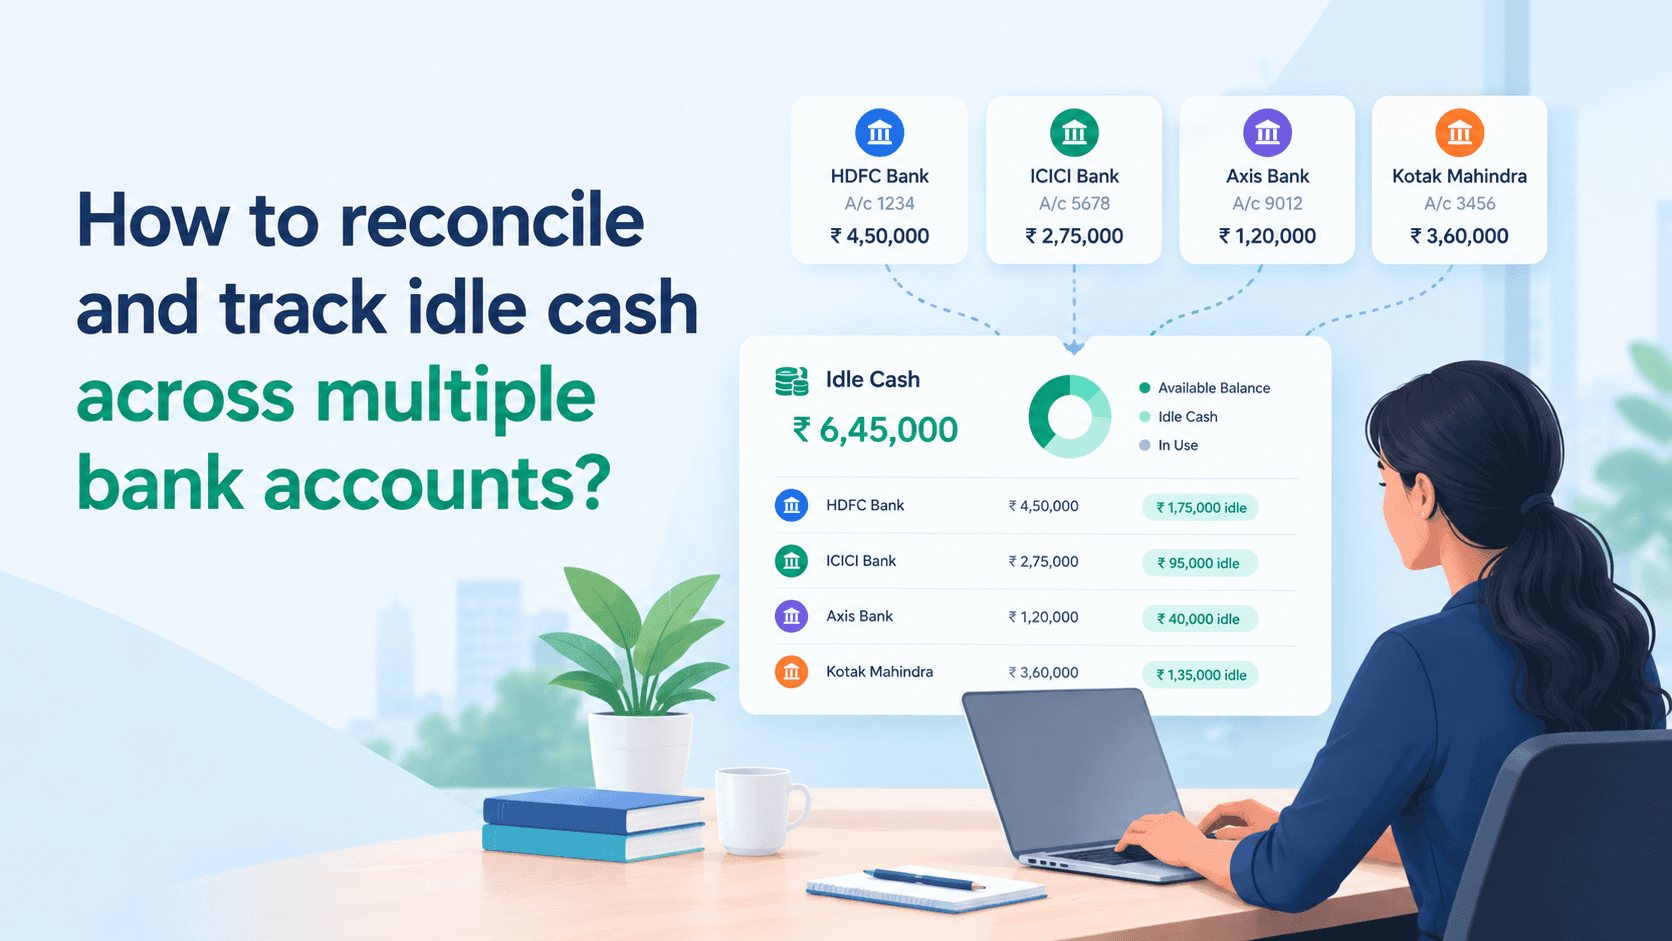
"We don't have visibility into our cash across accounts" usually gets treated as one problem, but it's really two. Reconciliation is about accuracy: does your internal ledger actually match what the bank shows. Consolidation is about visibility: can you see every account's balance in one place? A business can have great consolidation and still be reconciling badly; a single dashboard showing five account balances is only as reliable as the reconciliation behind each number. Good surplus cash management depends on solving both, in the right order.
This piece walks through what reconciliation actually involves, a practical workflow for doing it across multiple accounts, and how gaps in either process let idle cash sit unnoticed.
Reconciliation vsxx consolidation: Two different problems
Reconciliation happens at the level of a single account, matching every transaction on your bank statement against the corresponding entry in your books, so you can trust that account's balance is accurate. Consolidation happens across accounts, pulling multiple, individually reconciled balances into one combined view. Skipping straight to consolidation without solid reconciliation underneath just means your consolidated dashboard is confidently displaying numbers that might be wrong.
What cash reconciliation actually involves
At its core, reconciliation means comparing every transaction on a bank statement against your internal ledger, confirming that deposits, withdrawals, fees, and interest all match on both sides, and investigating any discrepancy until it's explained. Done properly, it isn't a once-a-month formality; it's the control point that keeps your reported cash position trustworthy.
Mutual fund investments are subject to market risk. Please read scheme-related documents carefully before investing. Past performance is not indicative of future returns.
The specific errors that show up across multiple accounts
A few error types recur specifically once a business is juggling more than one account. Timing differences are the most common: a payment clears the bank on the last day of the month but posts to your ledger the next day, creating a mismatch that isn't actually an error but looks like one. Transposition errors, entering ₹1,245 as ₹1,254, and omission errors, missing a transaction entirely during manual review, compound as transaction volume grows across accounts. According to a 2023 Gartner survey covered by global payments company XE, 18% of accountants admit to making financial errors at least daily, with over half making several errors a month, a rate that scales directly with how many accounts and transactions a single reconciliation process has to cover.
A step-by-step reconciliation workflow for multi-account businesses
Pull the statement for each account separately: Don't attempt to reconcile multiple accounts against a single combined ledger view; reconcile one account at a time against its own statement.
Match transactions line by line, flagging anything that doesn't have a clear counterpart in the ledger.
Investigate every unmatched item individually: A discrepancy is either a timing difference (resolves itself the next period), a genuine error (needs correcting), or something requiring follow-up with the bank.
Document recurring discrepancy patterns: If the same type of timing gap shows up every month for a specific account, note it so it's recognized quickly rather than re-investigated from scratch each cycle.
Sign off each account individually before rolling its confirmed balance into any consolidated view.
How reconciliation gaps hide idle cash specifically
This is the part that connects directly back to idle cash management. An unreconciled or poorly reconciled account often shows a balance nobody fully trusts, which means nobody confidently treats any portion of it as genuine surplus worth deploying. The caution is understandable, but it has a real cost: cash that might actually be surplus stays parked and untouched simply because the underlying number hasn't been verified. Reliable reconciliation is what actually lets a business identify genuine surplus with confidence, which is a prerequisite for the kind of audit we've covered here: How to identify idle cash in your business
Getting to a consolidated view once reconciliation is solid
Once individual accounts are reliably reconciled, consolidation becomes the easier half of the problem, pulling verified balances into one view rather than five separate logins. This consolidated, trustworthy view is also what a good rolling cash forecast actually depends on, since a forecast built on unreconciled actuals inherits all the same uncertainty. We've covered how that forecasting discipline works here: 13-week cash flow forecasting
Getting reconciliation right first, then building consolidation on top of it, is what actually makes a multi-account cash position something a business can act on with confidence, rather than a number that merely looks complete.
FAQs
1. How do you track cash across multiple bank accounts?
Start by ensuring each account is reliably reconciled against its own bank statement individually, then consolidate those verified balances into a single combined view rather than trying to track everything from one unified source without first confirming accuracy at the account level.
2. What is cash reconciliation?
Cash reconciliation is the process of matching every transaction on a bank statement against the corresponding entry in a business's internal ledger, confirming the two agree and investigating any discrepancy until it's explained.
3. How can businesses get visibility into idle cash across accounts?
By first reconciling each account so its reported balance can be trusted, then consolidating those balances into one view. Visibility without underlying reconciliation just means confidently displaying numbers that might be wrong.
4. What's the difference between reconciliation and consolidation?
Reconciliation is an accuracy check at the individual account level, confirming the ledger matches the bank. Consolidation is a visibility exercise across accounts, combining multiple already-reconciled balances into one view.
5. Why does poor reconciliation lead to idle cash going unnoticed?
An account balance nobody fully trusts tends to get treated cautiously, meaning cash that could genuinely be surplus stays parked rather than being confidently identified and deployed, simply because the underlying number hasn't been verified.
Back to all notes
Finance
5 mins
How much cash should your business keep? A guide to calculating your optimal cash buffer
There's no universal answer to how much cash a business should hold, but there are real, calculable methods for arriving at a number specific to your business. This piece walks through four approaches, from a simple rule of thumb to a formal economic model, and how to combine them into a practical buffer size.
Finance
4 mins
What Global Fintech Fest 2026 signals for the future of AI-native treasury
Global Fintech Fest 2026, held in Mumbai from September 8-11, built its entire agenda around agentic AI, alongside tokenization and quantum computing. The event itself wasn't treasury-focused, but the concept of agentic AI is directly relevant to what "AI-native" actually means for corporate treasury tools going forward. This piece covers what the event actually addressed, and draws the connection honestly rather than overstating it.
Finance
5 mins
Cash Sweep Accounts: How Automated Sweeps Work for Businesses
A cash sweep account links your current or savings account to a fixed deposit, automatically moving balances above a set threshold into the FD to earn interest, and moving funds back the moment the account needs them. This piece covers exactly how the mechanism works, what to check before setting one up, and where it falls short.