Idle Cash Investment
5 mins
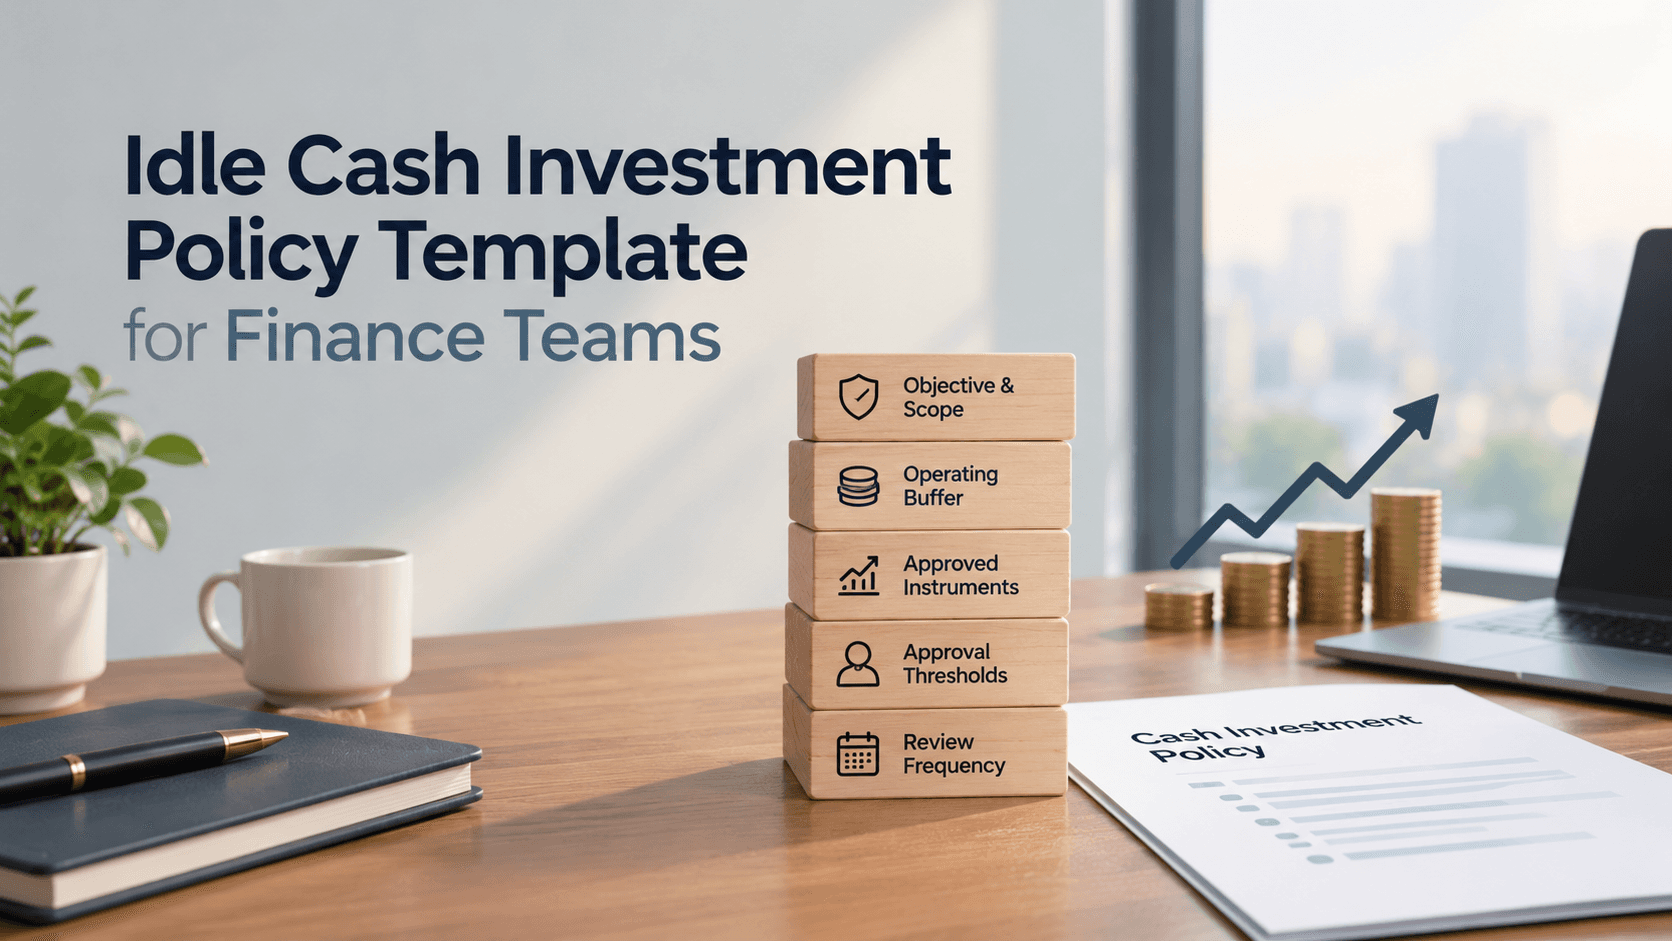
Most finance teams know they should have a documented cash investment policy. Fewer actually have one written down. Nordea's treasury research found that 92% of large corporates have a formal treasury policy, but that figure drops noticeably for smaller businesses, with some segments closer to 73-79%. That gap tends to track closely with how consistently a business actually deploys idle cash, since without something written down, decisions default to whoever happens to be paying attention that quarter. Good surplus cash management starts with closing that gap, and this piece is meant to make that genuinely easy to do.
Rather than another argument for why you should have a policy, this is the actual template, section by section, with what to put in each one.
What a cash investment policy actually needs to include
A working policy doesn't need to be long. It needs six things: a stated objective, a minimum operating buffer, defined risk tiers with approved instruments, clear approval thresholds, a review cadence, and sign-off from the right people. Everything below builds toward those six pieces.
Step 1: Define the objective and scope
Start with one or two sentences stating what the policy governs and why. For example: "This policy governs the management and deployment of surplus cash beyond the company's operating requirements, to preserve capital and maintain liquidity while earning a reasonable return." This framing matters because it sets the priority order explicitly: capital preservation and liquidity first, return second, which prevents the policy from later being read as permission to chase yield.
Step 2: Set the minimum operating buffer
State a specific number or formula, not a vague description. Something like: "The company will maintain a minimum operating buffer of [X months] of average operating expenses, or ₹[X], whichever is higher, in fully liquid accounts at all times." This is the line that everything else in the policy sits below; cash inside this buffer is never a candidate for deployment, regardless of what else the policy says.
Mutual fund investments are subject to market risk. Please read scheme-related documents carefully before investing. Past performance is not indicative of future returns.
Step 3: Define your risk tiers and approved instruments
This is the core of the document. List two to four tiers by time horizon, and name the specific instrument categories approved for each. For example: Tier 1 (0-2 weeks): overnight and liquid funds only. Tier 2 (2 weeks-2 months): liquid and money market funds. Tier 3 (2-12 months): money market funds, short-tenor FDs, high-rated corporate bond funds. Being specific about credit rating minimums here, restricting corporate bond fund holdings to AAA/AA-rated instruments, for instance, matters more than it might seem, since it's exactly the kind of detail that prevents yield-chasing later.
We've covered the underlying risk-return logic that should shape these tiers here: Understanding risk and return before investing business funds
Step 4: Set approval thresholds and authorised signatories
Define, in rupee terms, who can approve what. A common structure: amounts up to ₹X can be approved by the finance manager alone, amounts up to ₹Y require CFO sign-off, and anything above that requires board or committee approval. Name specific roles, not specific people, so the policy doesn't need rewriting every time someone changes positions.
Step 5: Set the review cadence
State explicitly how often the policy itself, not just the allocation, gets reviewed. Quarterly is a reasonable default for most businesses: "This policy will be reviewed every quarter, or sooner in the event of material changes to the company's cash flow, risk tolerance, or the interest rate environment."
Step 6: Get it approved and communicated
A policy that exists only as a draft on someone's laptop doesn't count. It needs formal sign-off from whoever the approval structure names- board, CFO, finance committee- and needs actually to reach everyone involved in cash decisions, not just sit in a folder.
For a broader look at the instrument categories your policy will likely reference, this covers the full landscape: Debt mutual funds
A simple template structure to copy
IDLE CASH INVESTMENT POLICY 1. Objective and Scope [1-2 sentences] 2. Minimum Operating Buffer [Specific amount or formula] 3. Risk Tiers and Approved Instruments Tier 1 (0-2 weeks): [instruments] Tier 2 (2 weeks-2 months): [instruments] Tier 3 (2-12 months): [instruments] 4. Approval Thresholds Up to ₹[X]: [role] Up to ₹[Y]: [role] Above ₹[Y]: [role/committee] 5. Review Cadence [Frequency and trigger conditions] 6. Approved By [Name/role, date] |
FAQs
1. What is a cash investment policy?
A cash investment policy is a written document that defines how a business manages surplus cash, its minimum operating buffer, which instruments are approved for different time horizons, who can approve deployment decisions, and how often the policy is reviewed.
2. How do you create an idle cash investment policy?
Start with a stated objective, define your minimum operating buffer, set risk tiers with specific approved instruments for each, establish approval thresholds by role, and set a regular review cadence, then get it formally approved and shared with everyone involved in cash decisions.
3. What should a corporate cash policy include?
At minimum: an objective and scope statement, a defined operating buffer, risk-tiered instrument categories matched to time horizons, clear approval thresholds, and a stated review frequency.
4. Who approves a cash investment policy?
This varies by business, but typically the CFO drafts it, and the board, a finance committee, or senior leadership formally approves it; the approval level is often tied to the size of the amounts the policy governs.
Back to all notes
Finance
5 mins
Idle Cash vs Working Capital: What's the difference and why CFOs mix them up?
Working capital is a specific accounting measure, current assets minus current liabilities. Idle cash is a subset of a business's cash balance that has no near-term purpose and isn't earning a return. The two get conflated often, but treating all working capital as untouchable, or all idle cash as part of the working capital buffer, both lead to real mistakes.
Finance
6 mins
Treasury Bills (T-bills) vs Liquid Funds: Which is better for Idle Corporate Cash?
Treasury bills and liquid funds are both low-risk, short-duration instruments, but they're structured very differently; one is a direct, held-to-maturity government security, the other is a professionally managed, NAV-based fund. This piece compares how they actually work, their returns, liquidity, and safety, and which fits which kind of corporate surplus.
Finance
6 mins
What is Ladder Strategy for Idle Cash?
A cash ladder splits surplus across instruments with staggered maturities, so a portion is always coming due while the rest continues earning at slightly better rates. This piece covers how the strategy works, how to build one using either FDs or short-duration fund categories, and a worked example for corporate surplus.