Finance
6 mins
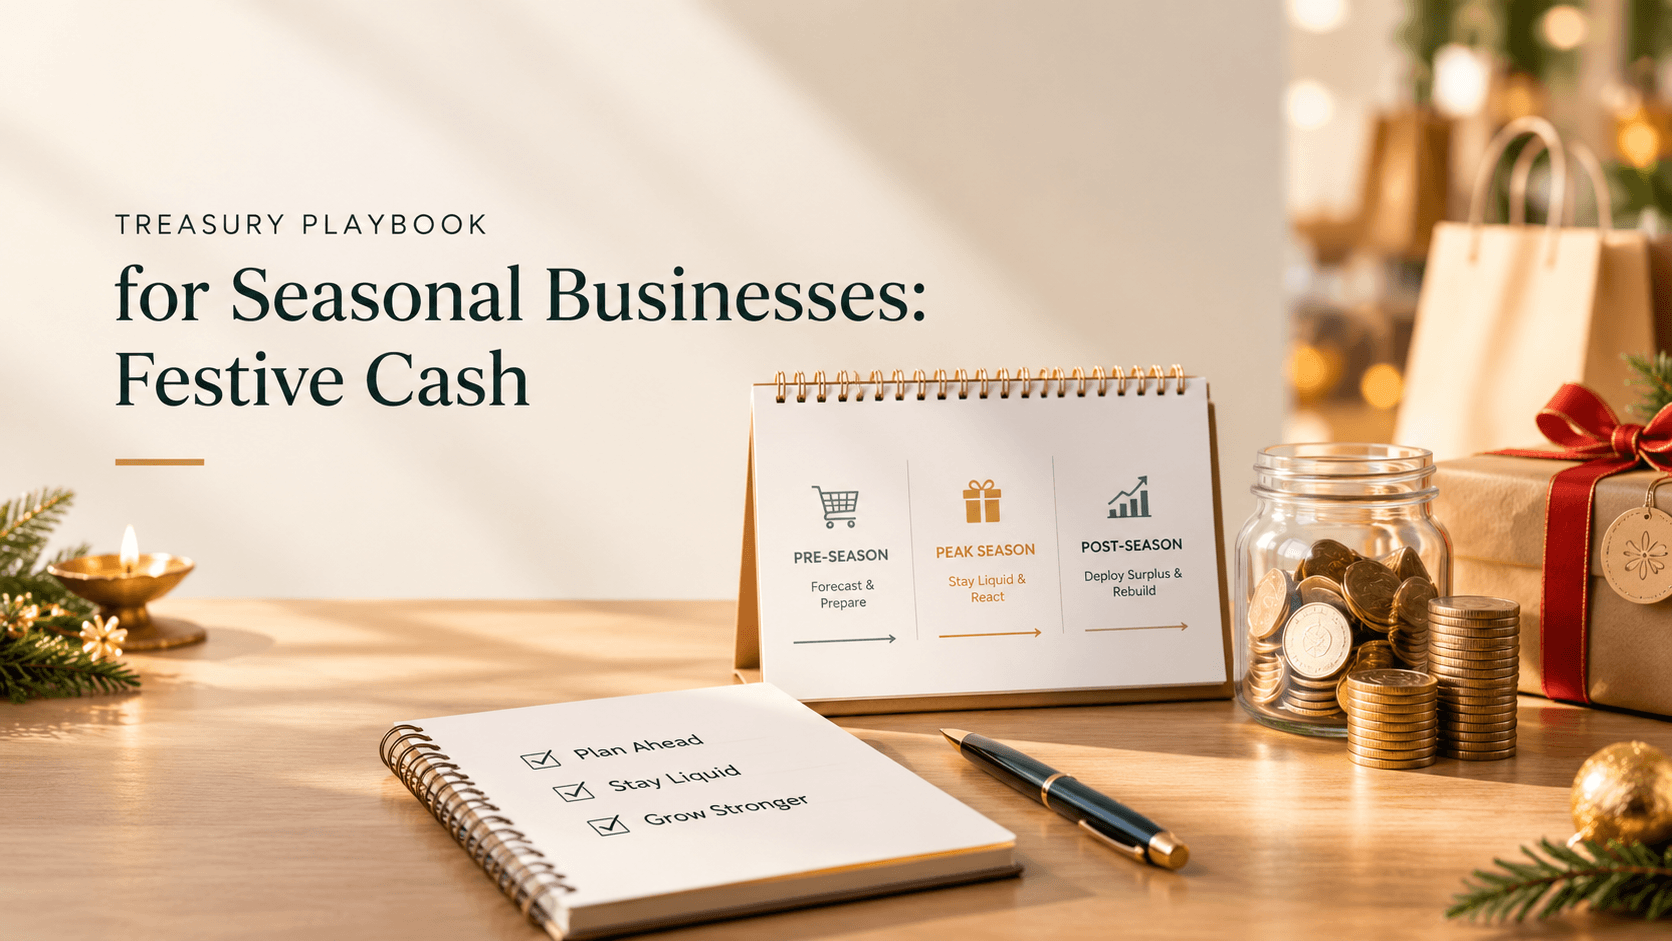
India's festive season isn't a minor seasonal bump for a lot of businesses; it's the single most concentrated commercial event of the year. Retail trade during the 2025 Navratri-to-Diwali window hit a record ₹6.05 lakh crore, a 25% jump over the previous year, according to CAIT. For businesses riding that wave, the treasury challenge isn't the size of the opportunity; it's that the spending, the surge, and the resulting surplus all arrive in rapid succession, with very little room to react if the cash position isn't planned ahead of time. Good idle cash management for a seasonal business looks meaningfully different from a steady, year-round company for exactly this reason.
This piece lays out a practical, phased playbook, what to do before the season, during the peak, and once it's over.
Why the festive season creates a unique cash flow problem
The core issue is timing, not scale. Seasonal businesses typically have to spend heavily on inventory, marketing, and temporary staffing well before the revenue actually arrives; festive hiring alone is projected to climb 15-20% this year according to TeamLease's Festive Season Workforce Report. That upfront outflow happens weeks or months ahead of the sales surge itself. Then, once the season peaks, revenue arrives quickly, but so does a fresh set of obligations, vendor settlements, logistics costs, and eventually returns and refunds that lag the original sale by weeks.
Phase 1: Pre-season, forecasting and buffer building
This phase typically runs from June through August for a Diwali-driven business. The priority is building an accurate forecast of festive-season inflows and outflows well in advance, not waiting until the spending has already started. A rolling, weekly forecast matters more here than at any other point in the year, since the gap between spending and revenue is at its widest during this window. We've covered exactly this kind of forecasting discipline here: 13-week cash flow forecasting: a practical framework for finance teams
Mutual fund investments are subject to market risk. Please read scheme-related documents carefully before investing. Past performance is not indicative of future returns.
Phase 2: Peak season, managing the surge itself
During the actual festive window, roughly September through Diwali and into early November, cash moves fast in both directions. Revenue accelerates, but so do replenishment costs as fast-moving inventory needs restocking mid-season, marketing spend often intensifies to capture last-minute demand, and payment terms with vendors and logistics partners can tighten during the industry's busiest period. The goal here isn't deployment; it's staying liquid and reactive, keeping enough of the inbound cash accessible to fund the next round of replenishment without a gap.
Phase 3: Post-season, deploying the surplus properly
This is the phase most seasonal businesses handle worst, not because it's complicated, but because exhaustion sets in right when discipline matters most. A strong festive season often leaves a business holding a genuinely large cash surplus by late November or December, and the temptation is to let it sit in a current account while attention shifts elsewhere. That's exactly the moment good idle cash management earns its keep, segmenting what's genuinely surplus from what's still needed to cover lagging obligations, then deploying the rest into short-term instruments rather than letting it sit idle through the quieter months that typically follow. We've laid out ten practical ways to do this here: 9 smart ways to earn more on idle cash
The specific risk: Looking flush but being fragile
A festive-season cash balance can be misleading. Returns and refunds on festive purchases typically lag the original sale by weeks, GST liabilities on the surge in sales come due on a fixed schedule regardless of how much of that revenue has actually settled, and credit notes with distributors or marketplaces often net out later than expected. A business that treats the full post-season balance as unrestricted surplus, without holding back for these known, lagging obligations, risks a liquidity squeeze precisely when it looks strongest on paper.
Building this into a repeatable annual playbook
The businesses that handle this well don't relearn the process every year. They document what worked, when pre-season forecasting should start, how much buffer to hold through peak season, and how quickly to deploy post-season surplus, so the following year's cycle starts from an established playbook rather than institutional memory that may or may not still be around. Given how reliably this pattern repeats annually, the upfront effort of documenting it once pays off every single year afterward.
FAQs
1. How should seasonal businesses manage cash flow before the festive season starts?
Build an accurate, rolling forecast well before spending on inventory and marketing begins, ideally two to three months ahead, since the gap between upfront costs and eventual revenue is widest during this pre-season window.
2. How can businesses manage liquidity during the actual festive season peak?
Prioritize staying liquid and reactive rather than deploying cash into longer-term instruments, since replenishment costs and vendor payment pressure typically intensify at the same time revenue is accelerating.
3. What should businesses do with surplus cash after the festive season ends?
Segment out what's needed to cover lagging obligations like returns, GST liabilities, and vendor credit notes first, then deploy the genuine remaining surplus into short-term instruments rather than letting it sit idle in a current account.
4. Why does a strong festive season sometimes lead to a cash squeeze afterward?
Because returns, refunds, and tax liabilities tied to the festive surge often settle weeks after the original sales, so a business that treats its entire post-season balance as available surplus can find itself short once those obligations come due.
5. How can seasonal businesses avoid relearning their cash management approach every year?
By documenting the playbook after each cycle, when pre-season forecasting should start, how much buffer to hold during peak, and how quickly to deploy post-season surplus, so the following year builds on an established process rather than starting from scratch.
Back to all notes
Finance
5 mins
India's GST Collections Hit ₹2.04 Lakh Crore in September 2026: What It Means for Business Liquidity
India's gross GST collections rose 14.7% to ₹2.04 lakh crore in September 2026, led by imports. For businesses, the real signal is in cash timing, not the headline.
Finance
5 mins
How are mutual fund returns taxed for companies in India? A CFO's guide
For companies, gains from debt-oriented mutual funds are taxed at the applicable corporate tax rate, whatever the holding period, with no indexation. Equity-oriented funds, including arbitrage funds, follow capital gains rates of 20% short-term and 12.5% long-term. Redemptions carry no TDS for resident investors, but dividend payouts do. This piece walks through each and how to compare options after tax.
Finance
5 mins
RBI's October 2026 MPC meeting: Will a rate hike change where you park idle cash?
The RBI's Monetary Policy Committee meets October 5-7, 2026, with the decision due October 7 at 10 AM IST. A Business Standard poll shows economists now expect a 25 basis point hike, following hawkish signals from the August meeting's minutes. This piece covers what's at stake, what a hike would mean for liquid fund returns, and what to do regardless of the outcome.